
A general reference to prepaid payments does not prove UKash is selectable for deposits on a specific casino account.
Why UKash Is Not a Verified Casino Cashier Option
UKash should not be treated as a confirmed payment method at any named UK casino. That is a narrower conclusion than saying that no casino accepts it: without a reliable cashier confirmation, it is not possible to identify a UK casino as a verified UKash option. For anyone comparing UKash casinos in the UK, the distinction matters. A payment method appearing in a general description is not the same as an available deposit choice on a particular account.
A cashier option is specific to the operator and the transaction. It needs to be shown as a method that can actually be selected, rather than inferred from a broad list of payment brands or from older descriptions. Casino payment arrangements can differ between sites, and a reference to UKash elsewhere does not establish that a UK player can use it at a particular casino now. Naming a casino without that confirmation would turn an uncertain claim into a recommendation.
This also means that the phrase “UKash casino” can describe more than one thing. It may refer to a casino that accepts UKash directly, a site that mentions prepaid payments generally, or a page that associates the brand with casino deposits without demonstrating a live cashier option. Those are not equivalent. Only the first would establish UKash as a usable cashier method; the other descriptions do not confirm that a deposit can be made through it.
The general payment picture should be kept separate from that question. UK casinos commonly accept debit cards, including Visa and Mastercard. A specialist casino-payment review may also list these card brands, but a list is not a guarantee that each card product will work for every UK customer. The payment option and the account’s eligibility still need to agree. That point does not make Visa or Mastercard evidence of UKash acceptance; they are separate methods.
UK Casino Payments: Methods and Options
Nor does the presence of familiar payment brands validate a UKash claim by association. A casino can support debit-card payments while offering no confirmed UKash route. Conversely, a page that discusses prepaid payment products does not establish that UKash itself appears in the cashier. The brand, the transaction method and the operator’s current cashier selection all need to match before a payment can reasonably be described as accepted.
This is why broad claims about UKash online casinos need careful reading. A page may use “accepted payments” as a general label, while its details refer to a different method or to payment availability that has not been checked against the UK cashier. If the claim does not identify UKash as a selectable option for the relevant casino, it leaves the central point unresolved. The wording may sound definite; the transaction evidence is what makes it definite.
For a direct answer to whether any UK casinos accept UKash, no casino can be named here as a confirmed example. That does not prove universal non-acceptance. It sets a boundary on what can responsibly be claimed: UKash is not established as a verified option at a named UK casino. “Still available” is therefore not a safe general description of UK casino cashiers, and it should not be inferred from older mentions or from a general payment-method category.
The same boundary applies to lists. A list headed “UKash casinos” implies that every entry has been checked for the specific method. Without confirmation at the cashier, including an operator would overstate what is known. A casino’s support for debit cards, or the appearance of a payment brand on a broad review page, cannot fill that gap. The practical result is simple: UKash should be regarded as unconfirmed, not as an established UK casino deposit route.
That wording is deliberately different from a claim that UKash is impossible to use anywhere. Availability is an operator-level detail, while the question concerns a current UK casino cashier. A definite answer would require a definite cashier option at a named site. Until that is shown, “UKash casinos in the UK” is a description that promises more than can be confirmed. The ordinary card methods listed by UK casinos remain separate facts, not evidence for UKash.
Market United Kingdom
Language English
Primary Topic UKash Casino Verification
Can UKash Still Be Used for Casino Deposits?
A UKash deposit would require the casino’s cashier to offer UKash as a payment method and accept the transaction through that route. A prepaid payment option with a similar purpose is not enough: payment brands and products are not interchangeable simply because both involve paying in advance.
That distinction matters when comparing UKash with Paysafecard. Paysafecard is a prepaid voucher used for casino deposits, but its availability does not establish that UKash can be used at the same casino. Nor does a general reference to prepaid payments confirm acceptance of a particular voucher. The method must be identified by name in the cashier’s payment options.
The same limit applies to casino games. A deposit method is not, by itself, a separate way to pay for online slots or live casino games. The payment is made into the casino account; whether the balance can then be used for a particular game depends on the casino’s own rules and the games it offers. A reference to slots, live tables or mobile play therefore does not establish that UKash is an accepted deposit route.
Prepaid vouchers also need to be assessed on the terms attached to the named product. Paysafecard is deposit-only: it can be used to put funds into an account, not as a withdrawal method. That is useful as a point of comparison, but it should not be transferred to UKash as though the products share identical terms. Each payment method has its own acceptance and transaction conditions.
This is why “prepaid accepted” is not a sufficiently precise payment claim. It describes a category, not a confirmed route for a particular brand. A casino may support one voucher while not supporting another, and a product’s presence at one operator does not establish its presence elsewhere. The distinction is practical: selecting a method that is not actually available can leave the intended deposit impossible to complete.
A useful check is whether the casino names UKash itself, rather than using a broad label such as vouchers or prepaid payments. If a payment page identifies Paysafecard, that is evidence only of the named Paysafecard option. It does not convert the listing into UKash acceptance. Likewise, the fact that both are prepaid does not establish that one can be used in place of the other.
Casinos That Accept Upaycard in the UK: What to Check
The same reasoning applies when a casino is accessed on a phone. A mobile site or app may present a cashier, but the device does not change the identity of the payment product. A general prepaid option on a mobile screen is not proof that UKash is available there. The relevant distinction remains the named method and the casino’s terms for that method.
For anyone comparing prepaid routes, the account should be assessed on two separate questions: whether the exact voucher is accepted for deposits, and what that voucher permits after funds reach the casino balance. Paysafecard answers the second question clearly in one respect—it is deposit-only—but it does not answer the first question for UKash.
A UKash option should therefore not be inferred from another voucher’s availability, from the word “prepaid”, or from the fact that a casino offers online slots or live games. Those are separate details. Only an explicit UKash listing would identify UKash as the selected deposit route; another prepaid product remains another product, with its own limits and terms.
Deposit Alternatives and the Cost of Bonus Eligibility
A practical alternative to a UKash deposit is not simply the method that moves money fastest. The relevant comparison has two parts: whether the cashier accepts the method for the account, and whether using it preserves access to the promotion being considered. A payment route can be convenient and still produce a worse overall offer if its use makes a bonus unavailable.
Debit cards, including Visa and Mastercard, are commonly accepted by UK casinos. They provide a direct route from a bank account, but card logos on a general payment page do not establish that a particular card product will work for a particular customer. Credit-card payments for gambling are prohibited at UK-licensed casinos; a credit card is not an alternative to a voucher for this purpose. The available card route is therefore subject to both the operator’s cashier and the rules applying to the card.
Casinos That Accept USDC in the UK: Payment Checks
PayPal is valued for speed and convenience, but a specialist review has reported that it may be excluded from bonus eligibility. That is a material condition, not a minor footnote: if a promotion depends on the deposit method, the convenience of PayPal has to be weighed against the value of the offer that would be forfeited. The condition should be checked against the operator’s own current terms before the deposit, since a review cannot establish the terms applying to every casino or promotion.
Open banking and bank transfers offer a different balance. A specialist review has described these routes as capable of providing instant deposits and fast withdrawals at many sites. That description is not a guarantee for every operator or transaction. Processing can depend on the casino and payment route, so the live cashier and the relevant withdrawal information matter more than a general label such as “instant”. Bank transfer may be useful where direct account funding is preferred, but it should not be treated as automatically faster or cheaper in every case.
Skrill and Neteller are available at some sites, and a specialist review has reported that they are often excluded from promotions. This makes them comparable to PayPal in one important respect: the payment route may be accepted while the promotional terms restrict the deposit. A method appearing in the cashier does not itself establish bonus eligibility. The offer’s payment-method exclusions need to be read separately from the list of accepted deposits.
The comparison is therefore not a ranking of wallets against bank transfers or cards. It is a check of the net terms for the intended transaction. For a promotion, that means confirming whether the chosen method qualifies before depositing. Without a promotion, the relevant points are whether the method is available, how it is funded, what the operator and provider charge, and whether the account currency will create conversion costs. A specialist review notes that costs can include casino charges, provider fees, bank or issuer fees, exchange-rate spread and network fees. A visible flat charge is not the entire cost; a conversion spread can be larger.
Debit Cards
Includes Visa and Mastercard, which are commonly accepted by UK casinos.
E-Wallets
Includes PayPal, Skrill, and Neteller, though some may be excluded from bonuses.
Bank Transfers
Includes open banking and direct transfers, often providing instant deposits.
There is no single lowest-cost option that can be identified independently of the amount and the account’s circumstances. The casino’s charge, the provider’s fee and any currency conversion must be considered together. Where the account balance and deposit are not in the same currency, confirming the account currency before the transaction can avoid an unexpected conversion. The deposit amount, fee basis and exchange rate determine the final debit; a method’s name does not.
“No-deposit bonus” describes an offer, not a payment method. It does not solve the question of which route to use for a later deposit, and it does not establish that any particular bonus is available. For a deposit-linked offer, eligibility turns on its stated conditions, including any excluded methods. For an offer that does not require a deposit, the deposit-method comparison is separate. No bonus value should be counted as part of the payment decision until the operator’s current terms confirm the offer and the applicable conditions.
For a UKash substitute, the useful comparison is thus conditional: a card may be widely listed, PayPal may trade convenience against bonus eligibility, and bank transfers or open banking may offer a direct route with timing that varies by site. Skrill and Neteller can be accepted at some casinos while still being excluded from promotions. The lowest-friction choice is the one that is available in the live cashier and fits the intended offer after fees and currency effects are included—not the one with the most attractive general description.
Prepaid Casino Deposits: What the Voucher Route Allows
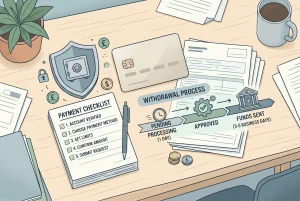
A prepaid voucher has a narrow role in a casino account: Paysafecard is a deposit-only method. It can be used to add funds, but it does not provide a route for withdrawing a balance. That distinction matters when comparing payment methods. A deposit option may complete one part of a transaction without solving how funds can later be paid out.
The practical constraint is therefore not just whether a voucher can fund a deposit. The amount accepted at the point of deposit also has to fit the account’s permitted range. A specialist casino review places the starting minimum deposit across payment methods in the £10–£20 range. This is a reported range, not a fixed Paysafecard threshold: the actual minimum depends on the method selected and the casino’s terms. A figure quoted for one payment route should not be treated as the voucher minimum at another site.
Casinos That Accept Klarna in the UK: What to Check
The upper end is less uniform. A specialist casino review notes that maximum deposits can be set per transaction, per day or per month, and that the applicable ceiling varies with both payment method and account status. Those are separate controls. A transaction cap limits one payment; a daily or monthly cap restricts the total deposited over that period. Account status can also affect the amount permitted, so a limit shown for one account may not apply to another.
For a prepaid casino deposit, the usable amount is consequently bounded at both ends: the minimum must be met, while the relevant maximum must not be exceeded. The exact figures are not interchangeable across sites or payment methods. Where the account shows a different threshold from a general review, the account’s own stated terms are the operative figures for that transaction.
Deposit-only also has a straightforward accounting consequence. A successful voucher deposit does not establish that the same voucher can receive a payout. The method’s function is limited to putting funds into the casino account; withdrawal arrangements are a separate matter. Treating a deposit label as evidence of two-way payment support would collapse two different transaction stages into one.
Prepaid funding can therefore suit a defined purpose—making a deposit—while remaining incomplete as an overall payment arrangement. Its limits are not only the amount accepted at deposit, but also the fact that it does not serve as a withdrawal channel. The relevant calculation is the amount the casino will accept, subject to the method and account limits, set against the fact that any later payout requires a separate route. A voucher’s prepaid status does not remove either condition.
Prepaid Payments on Casino and Mobile Cashiers
A prepaid option appearing in a general payment guide does not establish that it is enabled at a particular casino, for every account, or in its mobile cashier. The cashier is the relevant point of confirmation: payment methods can be presented differently by operator, account or device. A voucher route should therefore be treated as available only when the casino’s own deposit screen displays it and permits the intended transaction.
Casinos that accept Boku in the UK: payment guide
The same distinction applies to mobile access. A casino website may have a payment page that mentions prepaid payments, while the mobile cashier may show a narrower set of methods. A payment option seen on a desktop page is not proof that it can be selected in the mobile version. Availability should be checked in the interface being used, before buying or loading a voucher. Otherwise, the voucher may be ready while the casino has no matching deposit route.
There is also a difference between a method being named and a transaction being accepted. The cashier needs to show the payment route for the account in question, and the submitted payment details need to meet the operator’s requirements. A generic logo or a reference in a review page cannot confirm that a particular prepaid product, account or transaction will work. The amount of apparent compatibility is not the same as a completed deposit.
A specialist review of casino payment pages lists Visa and Mastercard, but that does not establish current UK availability for every customer or every card product. Those details need checking in the live cashier. The same discipline applies to prepaid methods: a label is a starting point, not a transaction confirmation. Payment pages can change, and eligibility may depend on the specific route shown at the time of deposit.
E-Checks at UK Casinos: What Payment Evidence Shows
Currency is another practical check before submitting payment. A specialist review of supplied casino pages reports support for GBP, but the account currency should still be confirmed before the first transaction. If the account is set to another currency, conversion may affect the amount charged or credited. The cashier’s displayed currency and the account settings should agree with the intended payment; a method’s presence alone does not settle that question.
For an online casino using prepaid vouchers, the useful check is therefore specific: open the deposit cashier, confirm that the relevant prepaid route is displayed, verify that it is available in the mobile interface if that is where the transaction will be made, and check the account currency before proceeding. This avoids treating broad payment information as a promise about an individual cashier. It also keeps the decision tied to what the operator actually offers at the point of payment, rather than to a method name appearing elsewhere.
What Changed Around UKash—and What the Record Does Not Confirm
UKash’s disappearance from current payment discussions does not, by itself, establish why the service was discontinued. A commercial decision, a change in ownership or a technical transition would each be a possible explanation, but none can be stated as the reason without reliable evidence. Treating one as fact would turn an unanswered point into a confident-sounding story.
Casinos That Accept Maestro in the UK: Payment Guide
The same distinction applies to the question of what replaced UKash in the UK. A payment method appearing in a casino cashier does not become a UKash successor merely because it also uses prepaid funds or serves a similar purpose. A direct replacement would require a demonstrated connection, such as an announced transfer of the service or a documented migration of customers and balances. Without that link, “alternative” and “successor” are not interchangeable descriptions.
One separate change is established: EcoPayz adopted the name Payz in 2022. That was a rebrand of EcoPayz, not evidence that Payz took over UKash. Similarity in the broad category of payment services does not establish continuity between the two brands. The name change therefore cannot be used to answer why UKash ended or to identify Payz as its direct replacement.
For casino payment decisions, the practical distinction is between a historical brand relationship and a method currently offered for a particular transaction. A rebranded service may retain a connection to its own former name; that does not make it a continuation of a different voucher system. Nor does a casino’s acceptance of one prepaid or digital payment product establish that another can be used there.
The sensible account of UKash’s status is consequently narrow: no specific cause of discontinuation or direct UK replacement should be presented as established. Payz’s 2022 rebrand can be stated on its own terms, without attaching it to UKash. This avoids confusing a documented name change with an unsupported claim of succession.
When a cashier names a payment method, its displayed terms determine whether it is available for that transaction. The historical resemblance of a product, its branding or its prepaid function cannot substitute for that confirmation. A replacement claim needs evidence of replacement; a similar label is not enough.
Our top casino picks for the UK
- EvoSpinBonus: 125% up to €2500 + 125 Free Spins · Payout speed: 1-3 business days
- ZombillionBonus: Welcome Pack 250% up to £4000 + 200 FS · Payout speed: 1-3 business days
- ChanzeBonus: Slots Welcome Bonus #1 200% up to €500 · Payout speed: 1-3 business days
- BritsinoBonus: Welcome Package – Get your £2,200 + 2,000 FS · Payout speed: 1-3 business days
- JetsetspinsBonus: 200% Bonus + 100 Free Spins + Free Royal Wheel · Payout speed: 1-3 business days
- Revery PlayBonus: 100% up to€1,000+ 100 FS · Payout speed: 1-3 business days
- NightWinBonus: £900 + 400 free spins · Payout speed: 1-3 business days
- DieselwinBonus: Welcome Pack 250% up to £4000 + 200 FS · Payout speed: 1-3 business days
- BeOnBetBonus: 100% up to €500 + 100 FS · Payout speed: 1-3 business days
- AmunbetBonus: Join now and get 450% up to 2,700 GBP + 450 FS · Payout speed: 1-3 business days
What UK Casino Payment Pages Actually List
A specialist review of UK-facing casino payment pages describes a varied set of payment categories: Visa and Mastercard, bank transfer, e-wallets and several cryptocurrencies. That is a description of what those pages mention, not a single cashier menu shared by every casino. The categories also differ in how specific they are: Visa and Mastercard are named card schemes, while “e-wallets” is a broad label covering a type of service rather than one named option.
Casinos That Accept E-Wallets in the UK: Payment Guide
The distinction matters when comparing casino payment information. A page that names bank transfer is referring to a different category from an e-wallet, even if both appear in the same payment section. Cryptocurrency is another separate category; the pages reviewed refer to several cryptocurrencies rather than treating them as one payment brand. A category label alone does not establish the precise service, terms or transaction route available at a particular operator.
UKash is not another name for any of those categories. Its appearance in a search for UK casino payment options should not be taken as evidence that a payment page lists it or that it can be used at a particular casino. The reported categories provide a useful outline of the payment types discussed on casino pages, but they do not identify a confirmed UKash cashier option.
The practical reading is therefore narrow: payment pages may mention card schemes, bank transfers, e-wallets and cryptocurrencies. The list does not establish that every casino offers every category, nor does a category label on its own answer whether a particular method is available to a UK account. Those are separate questions from the general shape of the payment information.
For a comparison focused on UKash, the relevant distinction is between a site discussing payment options in general and a cashier explicitly presenting UKash as a selectable method. The former does not prove the latter. A broad payment list can describe the range of methods covered by a page without confirming any specific UKash route.
Checking Whether a Payment Method Is Available Now
A payment method appearing on a casino’s general information page is not the same as appearing as an available option for a particular account. Payment menus can differ by operator, customer location and the details of the account. The live cashier is the practical check: it shows which routes the site makes available for the transaction being considered.
A specialist review lists Visa and Mastercard among the methods shown by the sites it examined. That listing does not establish that either card brand is available to every UK customer, or that every card product carrying the logo can be used. The cashier’s current options and the operator’s payment terms determine what is accepted; a brand name on a general page is not approval for a specific card.
Casinos that accept CashToCode in the UK: what to check
Card type matters in the UK. Credit-card payments for gambling are prohibited at UK-licensed casinos, including credit-card funding routed through a money service business. A Visa or Mastercard logo therefore cannot be read as permission to deposit with a credit card. The relevant question is whether the particular eligible payment route is available, not merely whether the brand is displayed.
The same distinction applies to searches about UKash. A general payment list, an old page or a third-party description cannot establish that UKash is accepted by a casino now. Current availability would need to be visible in the operator’s live cashier and confirmed in its terms. If the method is absent there, a mention elsewhere does not turn it into a usable deposit route.
A careful check therefore has two parts: confirm that the payment method appears in the current cashier for the relevant account, then confirm that the account and payment product meet the operator’s conditions. For cards, that includes distinguishing an eligible debit-card route from a prohibited credit-card payment. The cashier establishes what the operator is offering at that point; it does not make every product with the same payment-brand logo interchangeable.
Deposits, Withdrawals and the Original Payment Source
A payment method shown beside the deposit button does not automatically provide a route for withdrawals. Casinos may accept a method for funding an account while applying separate rules to payouts. For anyone assessing a UKash casino site, that distinction matters: a deposit claim alone says nothing about how winnings or returned funds could be paid.
UK anti-money laundering controls commonly require a payout to go back to the source used for the deposit. This closed-loop approach also supports anti-fraud checks. A casino may therefore return funds to the original payment route rather than let the account holder choose an unrelated destination.
Where the original source cannot receive a payout, an alternative may be considered, but additional verification can be required. That creates a practical dependency: the account holder may need to establish ownership of the replacement route and satisfy the casino’s checks before funds can be released. A payment method that works at deposit stage can still leave a gap at withdrawal stage.
Casinos That Accept AstroPay in the UK: What to Check
The relevant terms are those governing both directions of the transaction. They should identify whether withdrawals are supported through the same method, what happens when that method cannot receive funds, and whether another route triggers extra checks. Payment names on a cashier are not a complete description of the payout process.
This is also why a prepaid or voucher-style deposit should not be assumed to offer a matching withdrawal facility. Deposit and payout compatibility are separate conditions. The useful comparison is not simply whether money can enter the account, but whether the casino’s closed-loop rules provide a workable route for funds to leave it.
The 2026 UKash Search: Limits, Verification and Safer Account Controls
A UK casino account has checks that apply regardless of the payment method displayed in its cashier. Before a new customer can make a first deposit, the remote gambling operator must ask them to set a financial limit. The account must also provide accessible controls for managing those limits later. These are account safeguards, not evidence that UKash is accepted.
Payment ownership details matter separately. When the casino account and payment route are held in the same customer’s name, basic ownership checks are less likely to create avoidable transaction friction. A mismatch can complicate a payment review even where a cashier appears to offer a particular method. The practical check is whether the account details and the named payment route correspond.
Neither a financial limit nor matching ownership details establishes that a UKash option exists. UKash availability has to be confirmed as a payment method, while account controls and ownership checks govern other parts of the transaction. Treating one as proof of the other would confuse separate conditions.
For a current UK account, the order is therefore straightforward: confirm the payment method in the live cashier, review the operator’s deposit and account terms, set the financial limit when prompted, and keep the account and payment details consistent. The limit should reflect the amount intended for gambling, rather than being treated as a workaround for payment restrictions. These checks reduce avoidable account friction; they do not turn an unlisted method into an available one.
Why must withdrawals return to the deposit method?
UK anti-money laundering and anti-fraud controls commonly require casinos to return withdrawals to the original payment source. Using a payment route in the same customer’s name can also help avoid ownership-related delays.
What is the fastest withdrawal method for UK casinos?
PayPal, open banking services and debit cards linked to fast payout systems are generally among the quickest. The casino’s approval process and your verification status also affect how soon funds arrive.
Which payment methods are accepted in Great Britain?
UK casinos commonly accept Visa and Mastercard debit cards; PayPal, bank transfers and open banking are also used. Skrill and Neteller are available at some sites, and some UKGC-licensed casinos accept Apple Pay for deposits; check the cashier for current availability and eligibility.
Is Skrill available?
Yes, Skrill remains a common deposit method at UK-friendly casino sites, though availability varies by site and it is often excluded from promotions.